Buying at the Mount, refinancing a place you already own, or weighing up a move? I help people across Mount Maunganui and greater Tauranga get their home loan sorted in plain language, without the bank runaround.
You don’t always need to save 20% before you start looking. Tell me where you’re at and I’ll show you which low deposit options could work for you.
Lowest advertised special rate per term across NZ's main banks
Rates last updated: 24 October. Advertised special rates, minimum 20% equity, terms & conditions apply.
I help Mount Maunganui locals with every kind of home loan, whether it’s your first home or a better rate on the one you own.
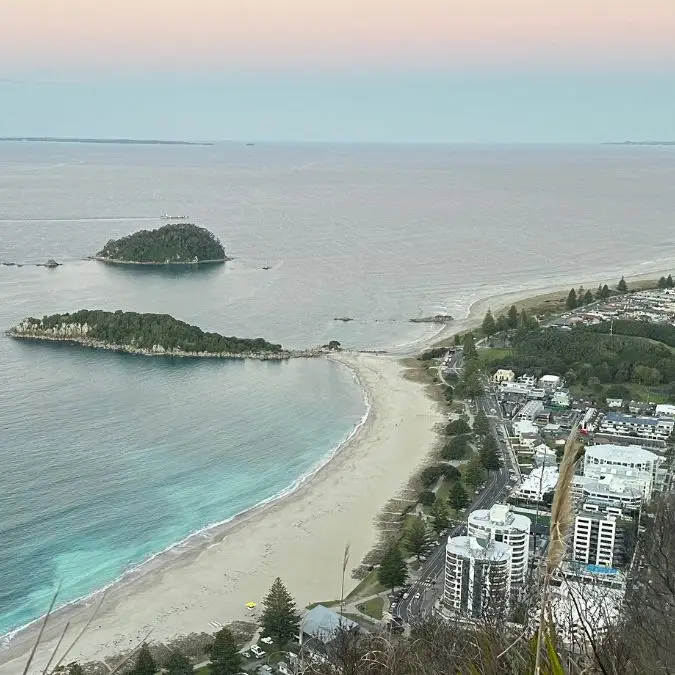
The Mount is one of the pricier corners of the Bay, so the deposit question really matters here. I work out how much you genuinely need and which low deposit route helps, so a coastal first home is not automatically out of reach.
If your fixed rate is ending on a Mount Maunganui mortgage, that is your window to change rate, structure or lender with no break fee. On a larger loan the difference is worth a proper review.
Trading up or down within the Mount, or moving in from elsewhere? Timing the sale and purchase is the real puzzle. I help you decide between selling first, buying first or bridging.
Renovating an older Mount property or building new both run differently to a standard purchase, with staged payments and different deposit rules. Talk to me before you commit to a contract.
A higher value coastal loan is not read the same way by every bank, and I place yours where it fits.
Conditions, questions and paperwork are mine to manage, not yours.
The lender pays me when your loan settles, whatever your deposit.
I believe mortgage advice should feel like a helpful conversation, not a finance lesson.
You can ask me anything. I’ll listen, explain things in everyday language and be honest about what looks possible.
I’ll handle the back-and-forth with the lender and keep you updated, so you don’t feel as though you’re chasing everyone yourself.
I’m a registered financial adviser, and helping first-home buyers and low deposit clients is the part of my job I love most.
As your mortgage broker I work with buyers across Mount Maunganui, greater Tauranga and right across New Zealand, from first homes to refinancing and new builds.
What people around the Mount ask me most.
Either works. Most people are happy on a phone call, video call or Zoom, and if you are around the Mount or greater Tauranga, meeting in person is easy to arrange.
Often, yes. Low deposit lending is my specialty, and schemes like the First Home Loan and shared ownership can bring a coastal purchase within reach. We work out exactly what your situation allows.
Yes, though a second property is assessed differently to an owner occupied home, with its own deposit and servicing rules. I match you to a lender whose criteria suit what you are buying and how you will use it.
Yes. On a larger coastal loan the gains from a better rate or structure can be significant, so when your fixed term ends it is worth a proper review rather than an automatic rollover.
Nothing, in almost every case. The lender pays me once your loan settles. If a fee ever applied, you would hear it from me first.
Not necessarily. Lenders assess income, credit and deposit differently, and a decline often turns on a single detail. It is worth a conversation before you rule anything out.