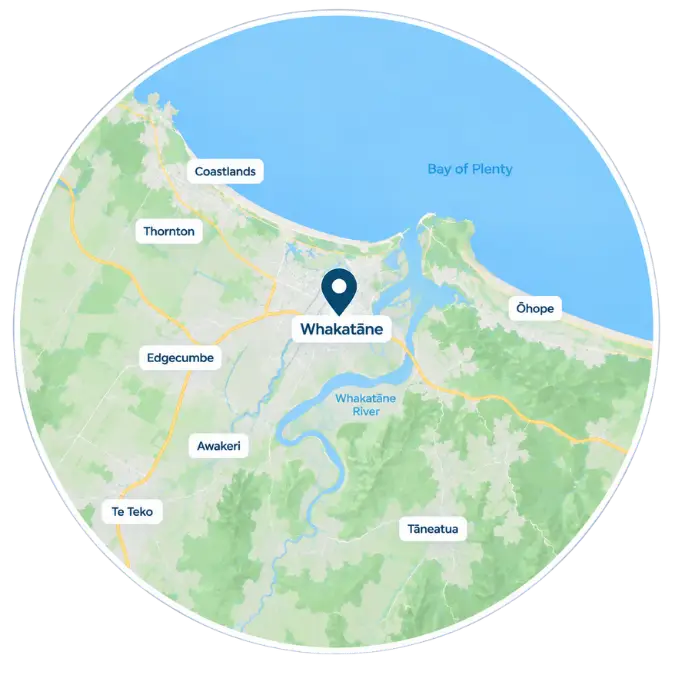
In Whakatāne and thinking about a first home, a move or a better rate? I help people across the Eastern Bay get their mortgage sorted without the runaround, and without sitting in a bank branch. Tell me your plan and I will lay out the real options.
You don’t always need to save 20% before you start looking. Tell me where you’re at and I’ll show you which low deposit options could work for you.
Lowest advertised special rate per term across NZ's main banks
Rates last updated: 24 October. Advertised special rates, minimum 20% equity, terms & conditions apply.
First home, a better rate, a move or a new build: here’s how I help Whakatāne locals get the right mortgage.
A first home in Whakatāne is more within reach than in the bigger coastal towns, so getting the deposit question right matters. I work out what you actually need and which low deposit route suits, from KiwiSaver to the First Home Loan.
Fixed rate ending on your Whakatāne mortgage? That is the one point where you can change rate, structure or lender without a break fee. Worth a proper look rather than a quick yes to the bank.
Upsizing within Whakatāne or moving in from a rural block? The hard part is usually timing the sale against the purchase. I help you weigh selling first, buying first or bridging.
Building in or around Whakatāne runs on staged payments and a smaller deposit than an existing home. Talk to me before you sign the build contract so the finance matches the schedule.
Banks read an Eastern Bay application differently, and I place yours where it stands the best chance.
The lender questions and the paperwork come to me, not to you.
The lender pays me once your loan settles, on any size of deposit.
I believe mortgage advice should feel like a helpful conversation, not a finance lesson.
You can ask me anything. I’ll listen, explain things in everyday language and be honest about what looks possible.
I’ll handle the back-and-forth with the lender and keep you updated, so you don’t feel as though you’re chasing everyone yourself.
I’m a registered financial adviser, and helping first-home buyers and low deposit clients is the part of my job I love most.
As your mortgage broker I work with buyers across Whakatāne, the Eastern Bay of Plenty and right across New Zealand, from first homes to refinancing and new builds.
What people in the Eastern Bay ask me most.
No. Everything runs by phone call, video call or Zoom, so the distance changes nothing about the advice or the lenders I can reach. Most of my clients do it this way.
For a lot of people, yes. Prices in the Eastern Bay tend to be gentler than the coast around Tauranga, so a given deposit goes further. What fits still depends on your income and the scheme you qualify for, and that is what we work through.
Sometimes 5 percent, through the First Home Loan or shared ownership. Low deposit lending is what I focus on, so we check every route before assuming you need more.
Yes. Lifestyle blocks and rural titles can need a lender who is comfortable with them, and part of my job is matching your situation to a bank whose rules fit rather than fighting one whose do not.
Nothing, in almost every case. The lender pays me when your loan settles. If that ever changed, I would tell you up front.
Often, yes. A decline usually comes down to one thing that can be explained or tidied, and lenders weigh income, credit and deposit differently. A short conversation is worth it before you assume it is a no.