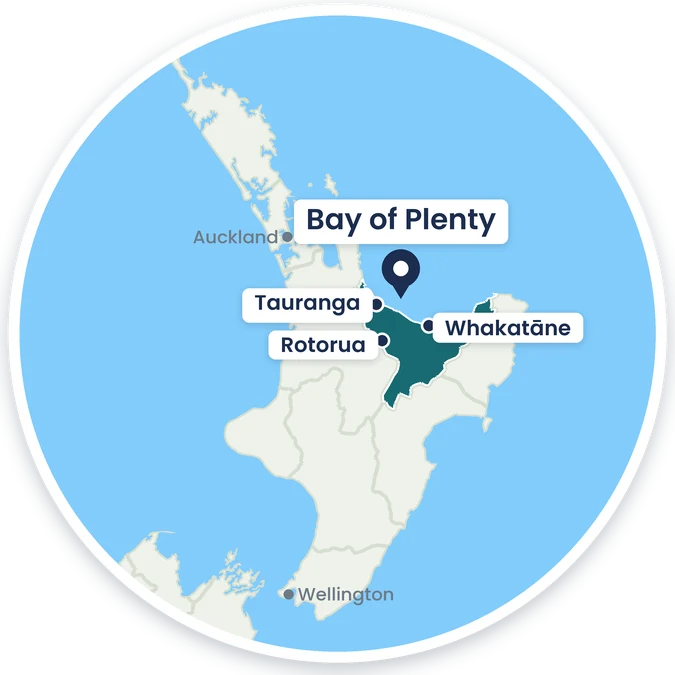
Buying, building or refinancing in the Bay of Plenty? I help people all over the region, in Tauranga, the Mount, Rotorua, Whakatāne and the towns in between. I will walk you through the real options in plain language and compare across most New Zealand lenders to find what fits.
You don’t always need to save 20% before you start looking. Tell me where you’re at and I’ll show you which low deposit options could work for you.
Lowest advertised special rate per term across NZ's main banks
Rates last updated: 24 October. Advertised special rates, minimum 20% equity, terms & conditions apply.
Wherever you live in the Bay of Plenty, I can help with your home loan. Start with the option that fits you best.
For most first home buyers in the Bay of Plenty, the deposit is the first hurdle. I work out how much you actually need and which low deposit route fits, from KiwiSaver to the First Home Loan.
Fixed rate coming to an end? That is your chance to change rate, structure or lender without paying a break fee. Before you accept the bank’s offer, have someone check it properly.
Moving within the Bay of Plenty, or into it from somewhere else? Getting the sale and the purchase to line up is usually the hard part. I help you choose between selling first, buying first or bridging.
Building a new home somewhere in the region? A construction loan draws down in stages, and a new build usually needs a smaller deposit than an existing house. Talk to me before you sign the build contract.
Each bank treats low deposits, new builds and self-employed income its own way. I match your application to the lender that suits it.
I handle the paperwork and the lender’s questions, so you are not the one chasing.
The lender pays me once your loan settles, whatever the size of your deposit.
I believe mortgage advice should feel like a helpful conversation, not a finance lesson.
You can ask me anything. I’ll listen, explain things in everyday language and be honest about what looks possible.
I’ll handle the back-and-forth with the lender and keep you updated, so you don’t feel as though you’re chasing everyone yourself.
I’m a registered financial adviser, and helping first-home buyers and low deposit clients is the part of my job I love most.
As your mortgage broker I work with buyers across the Bay of Plenty, in Tauranga, Mount Maunganui, Pāpāmoa, Rotorua and Whakatāne, and right across New Zealand.
What people across the region ask me most.
Both work. Most people are happy with a phone call, video call or Zoom. If you are in Tauranga, Mount Maunganui or Pāpāmoa, meeting in person is easy to arrange.
Often less than people expect. A 5 percent deposit can be enough through the First Home Loan or shared ownership, and low deposit lending is my specialty. We work out together what applies to you.
Yes. Construction loans draw down in stages, and new builds usually need a smaller deposit than an existing home. The part worth doing carefully is getting the finance sorted before you sign the build contract.
In almost every case, nothing. The lender pays me once your loan settles. If a fee ever applied, you would hear about it from me before we started.
Usually, yes. One lender’s decline often comes down to a single issue that can be explained or fixed, and other lenders look at things differently. Have a short conversation with me before you assume the answer is no.